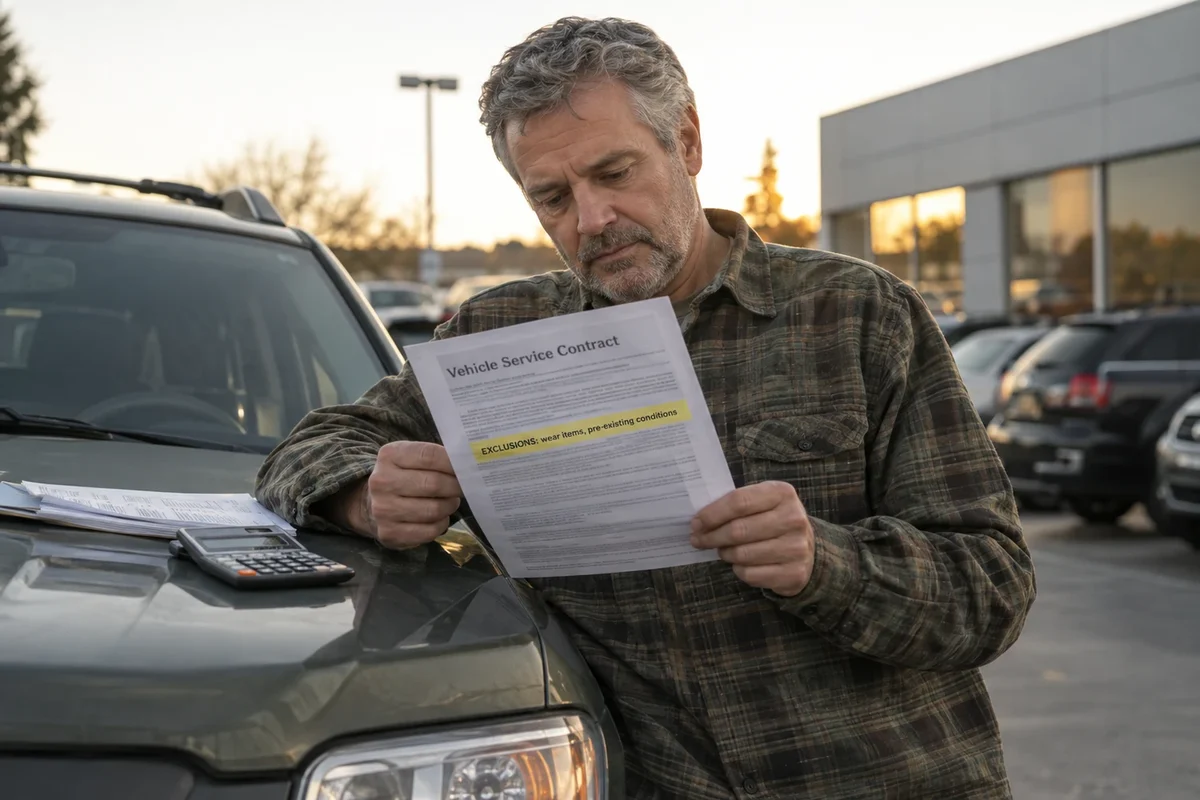
The pitch for an "extended warranty" on a used car is really a pitch for a vehicle service contract — a legally distinct product the FTC classifies separately from an actual warranty, and one that carries none of the federal warranty protections a real warranty does. Understanding that distinction changes how you should evaluate the offer, and the pricing math, sitting on the dealer's finance desk.
Warranty vs. service contract: the actual legal difference
A real warranty comes bundled into the price of the vehicle and carries federal warranty protections under the Magnuson-Moss Warranty Act. A vehicle service contract, sometimes marketed as an extended warranty, is an optional contract you purchase separately from a manufacturer, a dealer, or an independent third-party company — and because it's a contract rather than a warranty, its terms, exclusions, and enforcement mechanisms are whatever the specific contract says, not a federally standardized protection.
What these contracts actually cost
A yearly vehicle service contract commonly runs anywhere from $600 to more than $3,500, depending on the vehicle's age, mileage, coverage tier, and provider — and that's before the per-visit deductible you'll pay every time you actually use it. Multiply the annual cost by however many years of coverage you're being offered, then compare that total against a realistic estimate of the specific repairs your vehicle's age and mileage make plausible, using real repair-cost data for your make and model rather than a worst-case scenario the salesperson describes.
When the math tips against buying one
- The car is still under its original factory warranty — you'd be paying for coverage that's already free.
- You already keep, or can build, a dedicated repair fund with cash on hand — self-insuring is often cheaper over time than a service contract's markup and deductibles combined.
- You plan to sell or trade the car within a year or two — you'll have paid for years of coverage you never used.
- The contract restricts you to a narrow, inconvenient repair-shop network.
- The contract contains broad exclusions or 'cause and effect' carve-outs, where a failed part damages another part that isn't itself covered, leaving you to argue about which failure caused which.
When it can genuinely make sense
A service contract is more defensible on a vehicle known for expensive, complex repairs (certain European makes, some hybrid or EV drivetrain components) where a single covered repair could plausibly exceed the contract's full cost, on a vehicle you're planning to keep well past its original warranty and well into higher-mileage territory, or if you have no cash reserve at all and would otherwise face a forced high-interest loan for an unexpected repair. Even then, price the contract against a genuinely researched repair-cost estimate for that specific make and model — not the salesperson's anecdote about someone else's transmission.
Read the exclusions list before you read the coverage list
Every service contract's marketing leads with what it covers; the exclusions section is where the real value of the contract actually gets decided. Look specifically for wear-item exclusions (brakes, clutches, belts are commonly excluded even under 'bumper to bumper' branding), pre-existing condition clauses that let the provider deny a claim if a problem is deemed to have existed before the contract started, and maintenance-requirement clauses that can void coverage if you can't produce receipts for every recommended service interval.
The FTC Buyers Guide is where this should already be disclosed
Federal law requires dealers to post a Buyers Guide on used vehicles, which must indicate whether a vehicle service contract is available for an additional charge. If a dealer is pushing a service contract you weren't told about on the Buyers Guide, or pressuring you to decide before you've had time to review the actual contract terms, treat that as a red flag independent of whether the contract itself might otherwise be reasonable.
Watch for scam telemarketing pitches separate from legitimate dealer offers
The FTC has specifically documented telemarketing scripts using language like "Final Warranty Notice" or "Motor Vehicle Notification" designed to sound like an official manufacturer communication when they are not. A legitimate service contract offer from your dealer at time of sale is a different situation entirely from an unsolicited call or mailer claiming your factory warranty is about to expire — treat the latter with default suspicion regardless of how official it looks.
Cancel and refund rights if you change your mind
Most vehicle service contracts include a cancellation window, commonly 30 to 60 days or a low-mileage threshold from the purchase date, during which you can cancel for close to a full refund if you haven't yet filed a claim. Get the specific cancellation terms in writing before you sign, and calendar the deadline yourself — relying on the dealer or provider to remind you is not a reliable plan if you decide the contract wasn't worth it after reviewing the fine print at home.
Check the provider's financial backing, not just the dealer's reputation
A service contract is only as good as the company actually obligated to pay claims years from now, which may be a large, well-capitalized administrator or a much smaller company reinsured through an arrangement you can't easily evaluate from the sales floor. Ask specifically who the underwriting or administering company is (not just which dealer sold it), and do a basic search for that company's claims-payment complaints or state insurance department actions before committing, since a contract from a shaky provider is a real risk independent of how good the coverage terms look on paper.
Negotiate the price separately from whether you want the contract
The sticker price a finance manager first quotes for a service contract is rarely the floor — these products carry significant markup, and the price is often negotiable the same way the vehicle's own price is. Decide whether you want the contract at all before you start negotiating its price, and if you do want one, get a comparison quote from at least one independent third-party provider so you have a real number to negotiate against rather than accepting the dealer's first offer as fixed.